Economics is omnipresent in our daily lives, dictating how individuals, societies, and governments allocate their scarce resources. It influences everything from the decisions we make about work and spending to the public policies that shape our societal structure. Understanding the application of financial concepts in real-world situations can empower us to make informed personal decisions that not only affect our own lives but also contribute to the larger economic ecosystem.
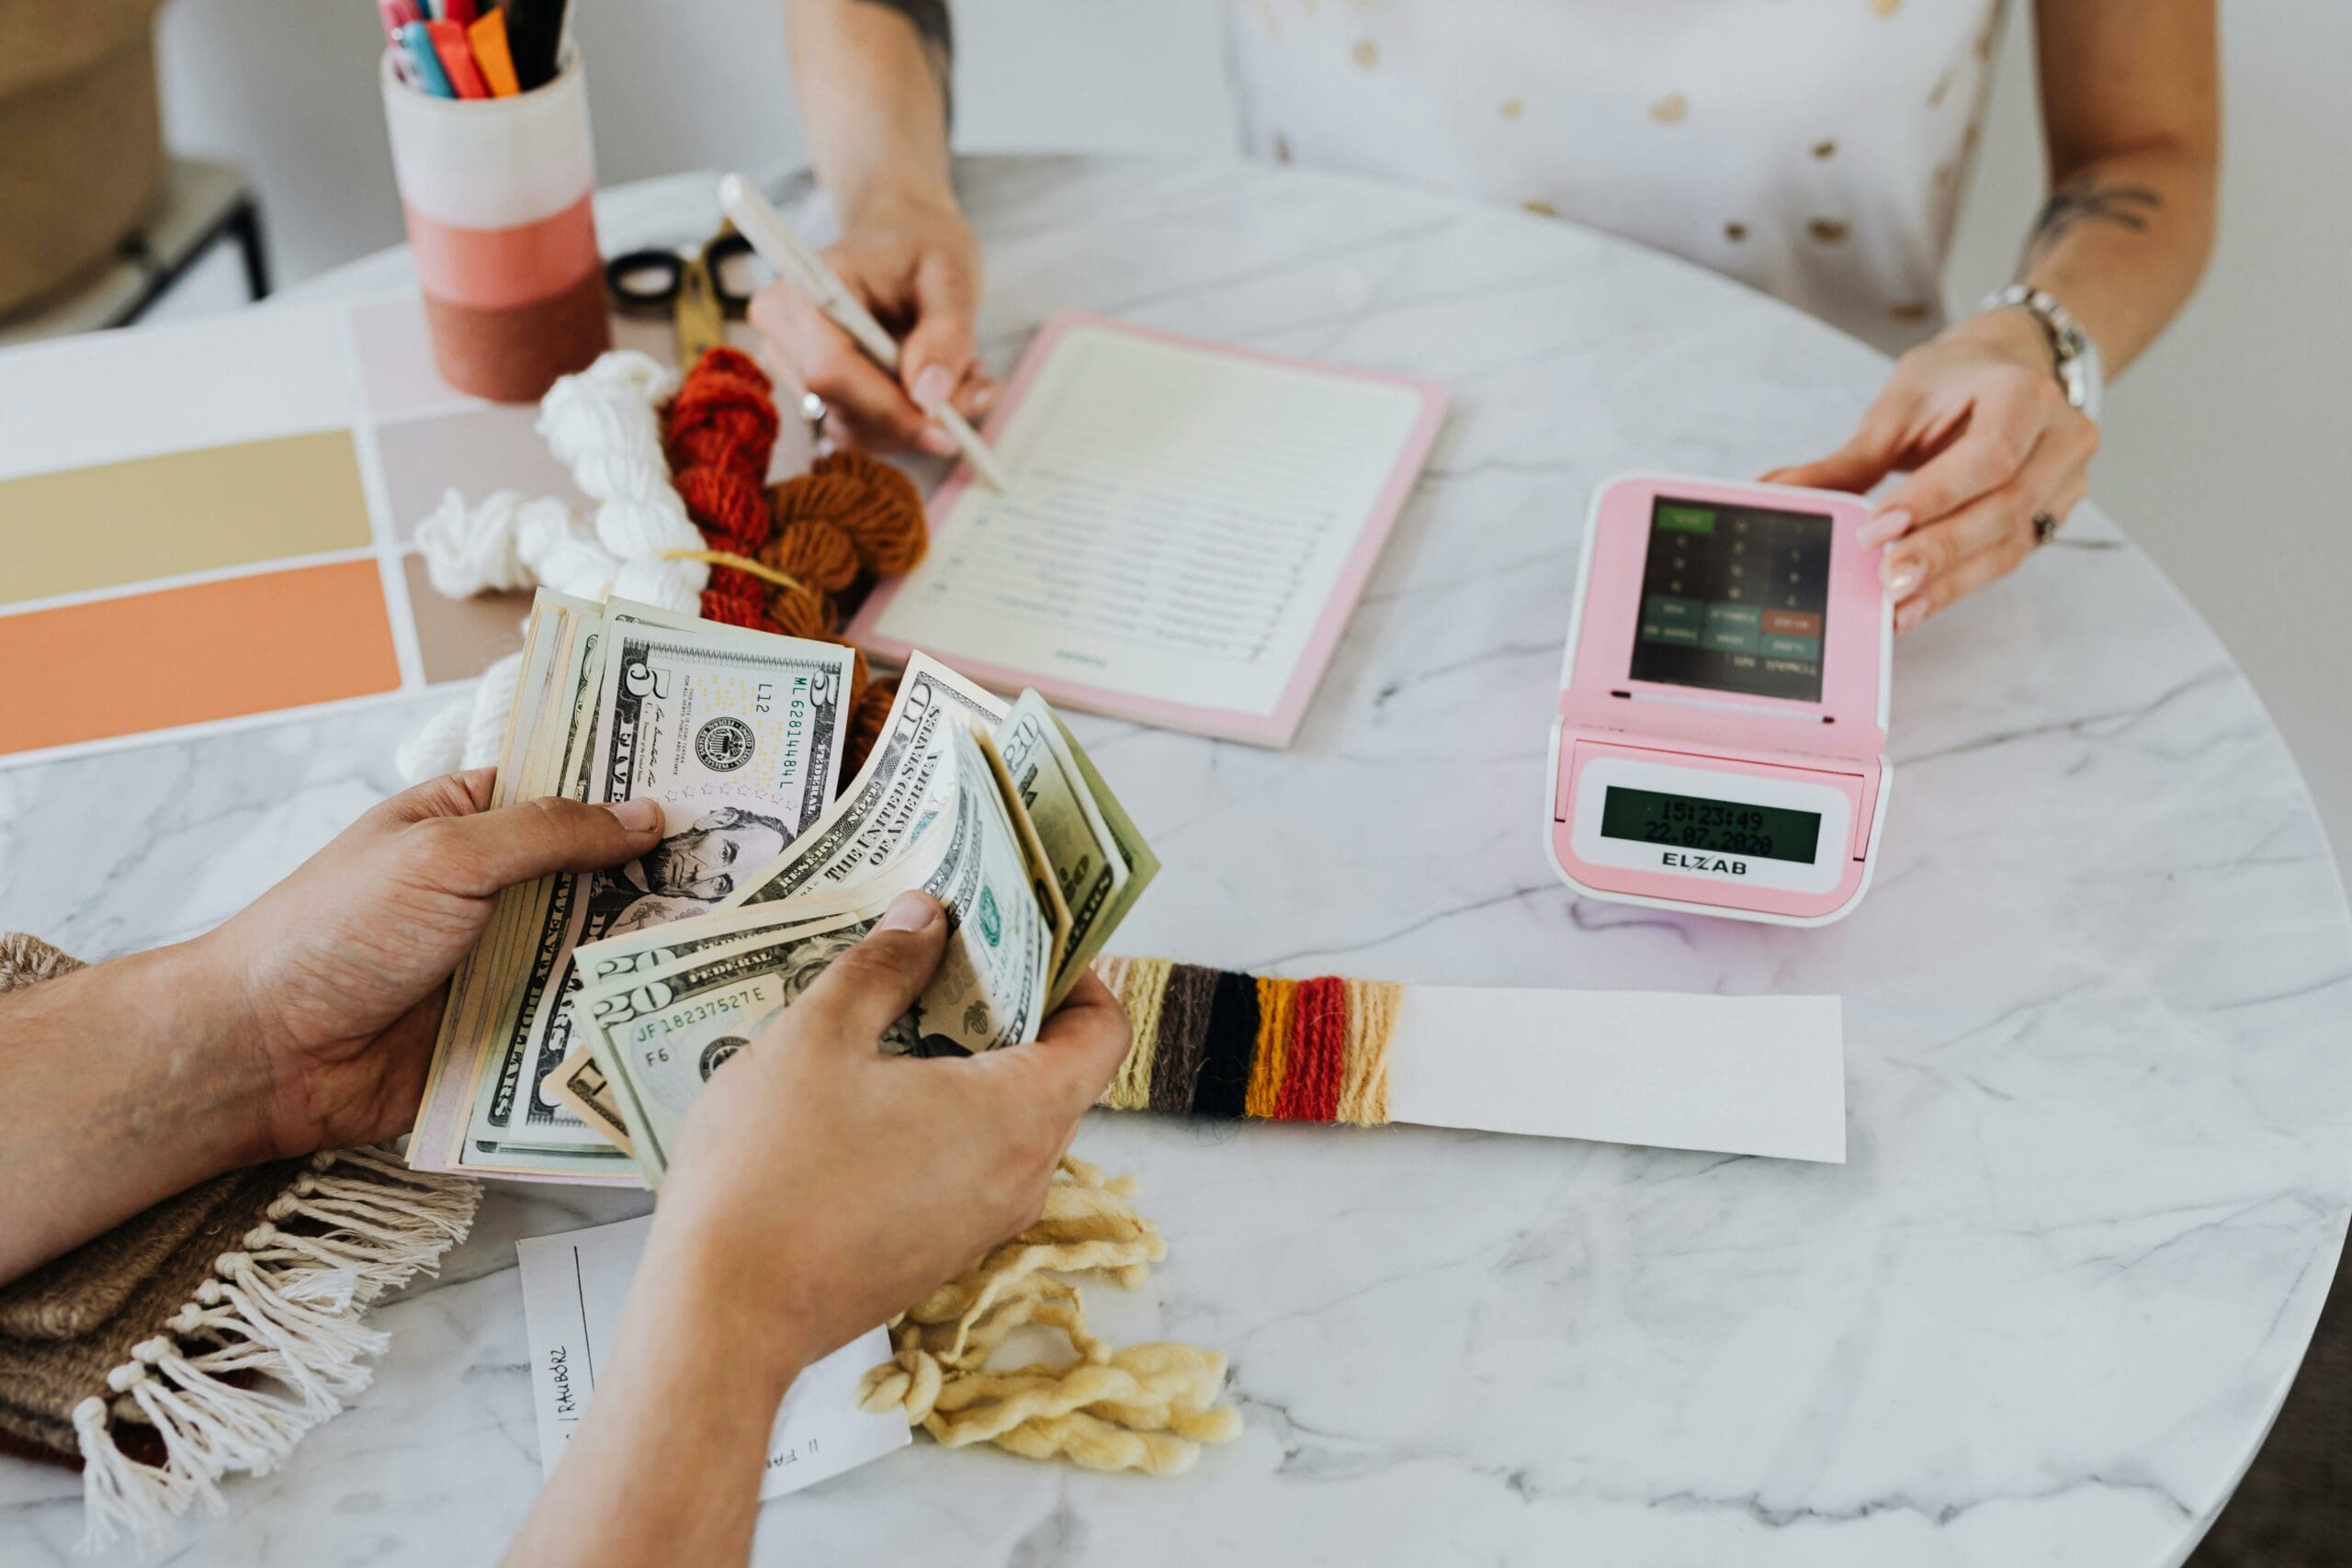
The Economics of Everyday: Hands holding US Dollar Bills
At the heart of economics lies the challenge of satisfying our infinite wants with limited means. Whether managing household finances, choosing the right investments, or navigating the complexities of credit and debt, the principles of economics guide us through these choices. As we go about our routine, the unseen hand of economics steers our consumption patterns, savings habits, and the pursuit of financial stability. It’s not just about making money; it’s about making smart decisions that enhance our financial well-being and, in turn, our quality of life.
Understanding Economics in Society
We live in a complex world where economics and society are deeply intertwined. The economy represents a system where various actors engage in the production, distribution, and consumption of goods and services. It is a network of interrelated activities that influence our daily lives and the societal decisions we make.
To comprehend this relationship, we must recognise that public goods and services—those that we collectively use and benefit from—are a vital part of our society. Streets, public parks, and basic sanitation are examples of public goods that do not diminish when more people use them. However, not everything our economy produces is as benign; we often face externalities. These are the by-products of economic activity that affect others who are not directly involved in the transaction. Pollution is a typical negative externality.
In the realm of macroeconomics, we’re looking at the economy on a grand scale, observing how different sectors interact, and how societal decisions, like setting interest rates or building infrastructure, influence the entire country’s or even the global economy. Our understanding impacts everything from our employment prospects to the prices we pay and the welfare of the nation.
We, as a community, benefit from grasping these economic concepts, applying them to not just understand the nature of our existence, but to forge pathways that lead to a more equitable and sustainable future. According to Michelle Connolly, educational consultant and LearningMole founder, “A profound understanding of economics empowers the public to make informed decisions that sculpt our communal destiny.”
Thus, by educating ourselves about the fundamentals of economics within society, we gain the ability to critically assess and influence the economic decisions that shape our world.
Making Personal Financial Decisions
When it comes to managing our personal finances, we need to engage in thoughtful decision-making that takes into account our overall budget and seeks to maximise our satisfaction. It’s not just about balancing the books; it’s about crafting a path towards financial stability and contentment.
Behavioural economics teaches us that individuals aren’t always perfectly rational in their financial behaviour. Various cognitive biases can influence our choices. Recognising this can help us correct for irrational tendencies and make better decisions.
Here is a simple structure that we can follow for effective financial decision-making:
Identify Objectives:
Define clear financial goals.
Gather Information:
Collect data relevant to the decision at hand.
Analyse Options:
Evaluate the potential outcomes of various choices.
Make the Decision:
Choose the option that aligns with personal goals and rational behaviour.
Execute and Review:
Implement the decision and periodically review its outcomes.
As Michelle Connolly, an expert with 16 years of classroom experience, says, “It’s essential to educate ourselves on personal finance from a young age, as it equips us with the knowledge to navigate the complexities of the real world.”
Our behaviour towards money defines much of our daily satisfaction, and by tackling financial decisions with a structured approach, we can strive to minimise bias and maximise contentment.
The Dynamics of Work and Employment
The landscape of work and employment is ever-evolving, with various forces shaping the way we understand and engage in our jobs. In this fast-paced world, it’s essential to consider how these changes affect us.
Firstly, the labour market is a dynamic entity, reflecting the supply and demand for workers. Industries rise and fall, and with them, opportunities for employment shift. The opportunity costs of choosing one job over another can greatly impact an individual’s career trajectory and personal life.
When industries experience growth, employment opportunities tend to increase, leading to lower unemployment rates. For example, as technology advances, new sectors emerge, requiring a workforce with modern skills. It’s our duty to adapt and prepare for these shifts in demand.
We’ve seen the concept of employment diversify. Today, traditional full-time roles coexist with part-time, freelance, or contract work. Each type of employment follows its own set of economic principles, influencing the decisions individuals make about their time and financial security.
Moreover, economic cycles influence unemployment, with recessions often leading to job losses. It’s vital for us to recognise these patterns to navigate our work lives effectively. During times of higher unemployment, the competition for jobs increases, emphasising the importance of continual learning and skill development.
Employment is not just about earning an income; it’s about creating value in our lives and for the economy. As Michelle Connolly, founder and educational consultant with over 16 years of classroom experience says, “Adapting to the changing nature of the labour market is essential for personal and national economic well-being.”
In conclusion, embracing the dynamics of work and employment is key. Staying informed and flexible allows us to achieve not just job security, but also personal fulfilment and professional growth.
The Role of Saving and Investment
The Economics of Everyday: Person putting coin in a piggy bank
Before we dive into the specifics, it’s crucial to understand that saving forms a secure foundation for our financial wellbeing, while investment is the catalyst that can potentially amplify our wealth over time.
Principles of Saving
We regard saving as the bedrock of financial stability. Consistently setting aside a portion of income not only cushions against unexpected expenses but also builds a reserve for future goals. The interest rate offered on savings accounts might be modest, yet it’s the compound interest over time that can significantly increase our savings. In essence, the earlier we begin to save, the more we could benefit from the power of compound interest, making it an essential tactic in financial planning.
Exploring Investment Options
When it comes to investing, we’re looking at a broad spectrum of assets where each carries its own risk and return profile. From stocks and bonds to property or even pension funds, these avenues can serve as instrumental tools in planning for our retirement. It’s paramount that we assess different investment opportunities with a critical eye towards diversification, balancing potential gains with the level of risk we are prepared to accept.
Michelle Connolly, a prominent educator with over 16 years of classroom experience, aptly states, “Investing in your financial knowledge is as important as investing in the market; both can yield prosperous returns in the future.”
Remember, both saving and investing are critical components that work hand in hand within the realm of financial planning, and taking a proactive approach to both can lead us towards a more secure and fulfilling future.
Credit, Debt, and Managing Finances
In managing our personal finances, understanding credit, debt, and making sound decisions is crucial. Let’s demystify these terms and see how they affect our everyday lives.
Credit refers to our ability to borrow money with the understanding that we’ll repay it later, typically with interest. For example, when we use credit cards, we’re taking a small loan that we agree to pay back within a certain timeframe.
Loans are a more substantial form of credit. Whether it’s for education or a mortgage, they allow us to cover major expenses by providing immediate funds with the agreement to repay over time.
Debt is the accumulated amount we owe. It can be seen as good – like that used to invest in a home – or bad, such as high-interest credit card debt. Managing our personal debt effectively involves understanding interest rates, repayment schedules, and our overall financial capacity.
Here are some strategies for managing finances wisely:
Budgeting: Track income and expenses to stay in control.
Savings: Allocate a portion of income to savings for unexpected costs.
Wise Credit Use: Use credit cards for convenience, not for deficit spending.
Timely Repayments: Pay debts on time to avoid penalties and maintain a healthy credit score.
By fostering a financial understanding, we empower ourselves to make decisions that ensure our financial stability. Michelle Connolly, a pioneer in providing educational resources states, “A sound grasp of financial concepts is akin to a compass in navigating the sea of personal finance.”
Remember, every credit agreement we enter requires careful consideration. Let’s commit to informed borrowing and disciplined repayment, thus securing our financial wellness.
Navigating Taxes and Personal Wealth
Managing personal wealth effectively involves understanding tax obligations and making informed decisions about major financial commitments like home-buying. In this context, financial literacy is crucial for individuals within an ownership society, where taking ownership of one’s financial future is highly valued.
When it comes to taxes, it’s important to know that they can significantly affect wealth accumulation. People can maintain their wealth more efficiently by learning about various tax incentives and how income tax, capital gains tax, and inheritance tax could impact their wealth. Engaging with financial advisors can offer essential guidance in navigating these complexities.
For those considering home-buying, understanding the tax implications, such as stamp duty and potential benefits like first-time buyer reliefs, is essential. Moreover, being financially literate helps to comprehend mortgage terms, interest rates, and the long-term financial planning required for such a commitment.
In an ownership society, where personal responsibility for financial well-being is emphasised, having a robust grasp of one’s finances is critical. As Michelle Connolly remarks, “Taking control of your financial future starts with education; it’s the bedrock of savvy wealth management.”
Below is a simple breakdown illustrating key aspects of managing taxes and personal wealth:
Aspect
Consideration
Income Tax
Understand personal allowances and tax brackets.
Capital Gains Tax (CGT)
Be aware of the annual exempt amount and rates for different assets.
Inheritance Tax (IHT)
Consider the threshold and potential for gifting assets.
Property Taxes
Factor in stamp duty and council tax for home ownership.
Tax Reliefs
Explore ISA contributions, pension schemes, and other reliefs.
Economics
In summary, we encourage individuals to pursue financial education to enable strategic managing and growth of personal wealth, while also planning for tax liabilities. Whether it’s through personal research, or seeking out professional advice, staying informed is key to navigating the financial landscape.
Consumption Patterns and Consumer Behaviour
In our day-to-day lives, understanding consumer behaviour is essential for not just individuals but also retailers and the broader market. Each consumer’s journey—from identifying a need to making a purchase—influences consumption patterns vastly. This interplay is crucial as it impacts market prices and product availability.
When it comes to major purchases like buying a car or buying a home, consumers often undertake a substantial evaluation. Such decisions typically involve exploring various financing options, assessing long-term value, and considering the economic implications of maintenance and operating costs.
Meanwhile, our everyday consumption choices, such as grocery shopping or clothing purchases, might be influenced by several factors, including sales promotions, peer recommendations, and personal needs or aspirations. Such routine decisions, though appearing trivial, cumulatively shape market trends and demand cycles.
Michelle Connolly, an authority with over 16 years in the educational sector, articulates this interplay: “As consumers, we’re not just buying products; we’re often buying experiences and identities that come with them.”
Retailers must adeptly respond to these trends by adjusting their stock levels, marketing strategies, and pricing schemes. An astute understanding of consumer behaviours can support retailers in creating value propositions that echo with their target audience’s evolving needs.
Ultimately, our choices as consumers reflect broader economic patterns, signalling our values and priorities through the very act of consumption. As such, the study of consumer behaviour extends far beyond mere transactions, highlighting its importance in shaping both the economy and society.
Analysing the Banking and Credit System
In the intricate world of finance, understanding the banking and credit system forms the backbone of our economic dealings, influencing everything from savings accounts to large-scale business loans.
Understanding Banks
Banks operate as the cornerstone of financial stability, providing a secure place for individuals and businesses to deposit money. Their pivotal role in the economy is underscored by their ability to manage the flow of money through savings and checking accounts, extend credit, and facilitate payments and investments. Importantly, they’re regulated entities, often backed by national insurance schemes, which maintain the trust we place in them. Economists closely monitor interest rates set by banks, as these rates ultimately shape consumer spending and inflation.
Interest Rates play a crucial role by influencing the cost of borrowing and the reward for saving. For instance, a hike in rates typically discourages borrowing and encourages saving, which, as conventional wisdom suggests, can slow down economic activity. Conversely, lower interest rates tend to stimulate spending and can lead to economic growth.
Credit System Explained
The credit system is a networked structure enabling the flow of capital from those with surplus funds to those in need of funds, essentially governing borrowing and lending. Credit is extended by a myriad of financial institutions, not limited to banks but including credit unions, building societies, and other specialised lenders. It’s a dynamic which ripples through the economy impacting everything from individual purchasing power to the health of entire industries.
The health of the credit system is often gauged by looking at the quality and performance of various forms of debt, such as personal loans, mortgages, and bonds. A well-functioning credit system is marked by a balance between prudent lending and accessible credit for consumers and businesses.
In our examination of these financial pillars, we see how they intertwine and underpin both everyday transactions and long-term economic strategies. Our ability to navigate these systems confidently can make a significant difference in our financial health and the broader economic landscape.
Economic Challenges: Inflation and Recession
In our day-to-day lives, we often feel the ripple effects of larger economic trends, particularly inflation and recession. Inflation is the increase in prices over time, which erodes the purchasing power of our money. Simply put, each pound buys a little less. This can impact everything from our grocery bills to the cost of our utilities.
On the other side, a recession is marked by a significant decline in economic activity, typically seen in GDP contraction, high unemployment, and a drop in the stock market. During a recession, businesses may struggle to sell their goods and services, individuals may lose their jobs, and consumer spending usually falls.
Here’s how these challenges can affect everyday financial concepts:
Low-interest rates: In response to a recession, the Bank of England might lower interest rates to encourage borrowing and spending, aiming to stimulate the economy.
Stock market: A high inflation rate could lead to market volatility, as investors worry about their returns being eroded. During a recession, stock prices generally decline as companies’ growth prospects dim.
External costs: Both inflation and recession can increase external costs such as higher loan rates or reduced investment in public services, indirectly affecting our finances.
GDP: As a gauge of overall economic health, GDP directly impacts government spending and policy decisions relating to taxation and public services, which in turn affect our wallets.
Our own Michelle Connolly, founder of LearningMole and an enthusiastic educator with a robust 16 years of classroom experience, puts it this way: “Economic fluctuations like inflation and recession aren’t just for economists to worry about; they’re real challenges that require us to adapt our approach to daily finances and long-term planning.”
By understanding these concepts, we’re in a better position to navigate the financial waves and make informed decisions.
The Concept of Value and Pricing
In our daily transactions, the idea of value is central to understanding economics. It’s the worth that is assigned to goods or services and is often reflected in the price. Price, then, is a measure of value, determined largely by supply and demand. When a product is scarce but in high demand, its value and price increase. Conversely, if there’s a surplus of an item with little demand, the price generally falls.
Understanding costs is essential, for they impact prices too. Costs refer to the expenditure a company incurs to create a product or service, which in turn influences the price at which the item is sold. For a business to sustain, the sale price must cover these costs and yield a profit.
Resource allocation is the process by which society manages its scarce resources. It is influenced by the prices of different goods and services, which signal where resources are most in demand and where they can be most productively used.
When studying economic theories, these concepts may seem clear-cut. Yet, Michelle Connolly, founder of LearningMole, states, “Real-world pricing is complex; it bridges economic models and human behaviour, reflecting not just costs and scarcity but perceptions of value too.”
It is vital for us to grasp the interplay between value and price as it applies to an array of decisions, from personal purchases to major business investments. A sound comprehension of these economic underpinnings equips us with the tools to navigate the financial landscape of everyday life.
Preparing for the Future: Insurance and Risk
When we talk about the future, it’s vital to address the management of risk. Risk pertains to the probability of encountering unforeseen losses. Insurance is a key tool that shields us from financial jeopardy, turning uncertainties into something manageable.
In our daily lives, from buying a house to driving a car, we are exposed to potential financial distress that can arise from unpredicted events. Here are some aspects of insurance and risk that deserve our attention:
Insurance Types: There’s a policy for varying risks:
Life Insurance
Health Insurance
Property and Casualty Insurance
A comprehensive understanding of these helps us match them to our needs, securing our financial well-being.
Financial Planning: Securing insurance is part of broader financial planning. It’s about ensuring that liabilities, like debt exposure, don’t escalate into crises. A sound plan encompasses savings, investments, and insurance to cover potential financial risks.
Future Security: Our tomorrow hinges on the decisions we make today. Insurance gives us peace of mind, knowing that we, or our dependents, won’t be financially crippled by accidents, illness, or unplanned events. It’s a cushion against the shocks.
As Michelle Connolly, the founder of LearningMole, aptly puts it: “Understanding the economic frameworks that surround us is crucial. It prepares us for life’s twists and enables us to stand firm against the currents of financial uncertainty.”
In essence, we foster a secure financial future by mitigly the impact of potential adversities. This responsible approach ensures that the avenues we venture down are less daunting, preserving our hard-earned stability.
Frequently Asked Questions
In this section, we’ll explore how economic principles can apply to everyday life, helping to make sound financial decisions and understanding our daily habits better.
How can understanding economics help with day-to-day financial decision-making?
We know that grasping basic economic concepts can empower us to make informed financial choices. For example, by understanding the principle of supply and demand, we’re able to decide when it might be more cost-effective to purchase seasonal goods.
What are some examples of economic principles at work in daily shopping habits?
Our daily shopping is influenced by economic principles like scarcity and consumer confidence. “When items are scarce, we’re more likely to buy them quickly, perhaps without searching for the best deal,” explains Michelle Connolly, a seasoned educational consultant.
Could you explain the role of opportunity cost in our everyday life choices?
Every time we make a choice, we face an opportunity cost—the benefits we give up by choosing one alternative over another. If we opt to spend an evening studying an investment course instead of going out, the cost is the lost leisure time.
How does behavioural economics explain the financial decisions we make on a regular basis?
Behavioural economics suggests that we’re not always rational. Connolly states, “Our emotions and psychological biases often lead us to make impulsive purchases or overvalue items on sale, even if we don’t need them.”
In what way does financial literacy shape our personal economic well-being?
Being financially literate means we’re more likely to budget effectively, understand interest rates, and avoid debt. “It’s the shield against the marketing that encourages us to spend more,” Connolly reflects.
What practical tips from economics can assist in better budgeting and saving?
Economics teaches us the importance of diversification and the time value of money. By spreading investments and saving early, we benefit from compound interest and reduce financial risk in our future.
Maths Circus, an innovative platform we've crafted, presents a captivating realm where children learn mathematics through the exciting theme of a circus. The joy of juggling numbers and solving circus...
Athena was the ancient Greek goddess of wisdom, strategy and defensive warfare, and the protector of the city of Athens, which still carries her name. In the stories the Greeks...
The Mysterious World of Bees: Bees are stranger and cleverer than most children expect, and the UK alone is home to around 270 bee species. Only one of them is...
Fruit helps protect the body from disease because it delivers fibre, vitamins, minerals and natural plant compounds that support the heart, the gut, blood sugar control and healthy cells. The...





Leave a Reply